

Skrill - Fast, secure payments
Paysafe Holdings UK Limited
- 4.6
- 3.72K Reviews
- 10.00M
- Downloads
- Free
- Price
Screenshots
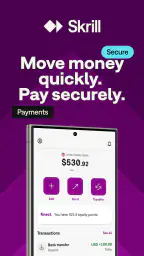
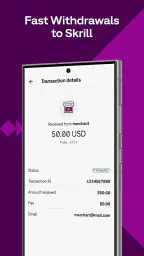
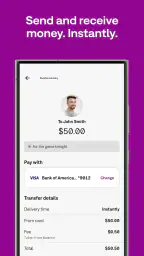
Skrill - Fast, secure payments Pros and Cons
Pros
- Fast and secure transactions worldwide
- Supports multiple currencies for flexibility
- User-friendly interface for easy navigation
- Instant notifications on transactions
- Advanced fraud prevention features
Cons
- Limited customer support availability
- Higher fees for international transfers
- Account verification can be time-consuming
- Not widely accepted as PayPal or others
- Some features may be region-restricted
 Analysis by All-app
When I choose a money app, I start with a practical question: will the person or service I need to pay actually accept it, and can I move money in a way that suits my routine? A polished interface matters, but it cannot make up for a payment route that does not fit. Skrill is most appealing when you want a phone-based account for transfers and online payments, particularly if you already encounter it among the payment options you use.
I would also decide how often I expect to use it before making it part of my financial routine. A separate payment app can be convenient for occasional transfers, but keeping another account means another place to check balances and review activity. For me, that trade-off is worthwhile only when the app makes a recurring task simpler rather than adding a step to every purchase.
Start with the payment route, not the feature list
Before relying on Skrill, I would check that the other person or the service supports the kind of payment I want to make. This is especially important for an international transfer: the app’s currency tools may help, but a useful outcome still depends on the destination and the costs involved. I would review the amount, currency and any displayed charges before confirming, then compare the final result with another way of paying if the transfer is significant.
That habit is useful even for everyday spending. A payment that looks straightforward at the confirmation screen can still have a different overall cost from paying directly with a bank card or using a bank’s own transfer service. I treat the displayed transaction details as part of the decision, not as fine print to rush past.
Fit it to a real routine
Imagine splitting a shared expense with someone who already uses Skrill. Rather than working out a cash handoff, I could use the app to send the payment and later check the transaction history if I needed to remember what I paid. That is a modest convenience, but it is exactly the sort that makes a finance app useful: it removes a small point of friction without requiring a complicated new system.
For online purchases, I would use it when Skrill is offered at checkout and I want to keep that payment activity distinct from everyday card spending. I would still keep a familiar alternative available. If the merchant does not support the app, or if a direct card payment is quicker and clearer, there is little reason to force the transaction through another account.
Where it sits among alternatives
Skrill belongs to the broader group of digital payment and money-transfer apps, but it is not automatically the best answer for every payment. A bank app may be more convenient when both people already use the same bank or when I want transfers and the rest of my finances in one place. A card or mobile wallet can be simpler for routine purchases where it is accepted, while another transfer service may be a better fit when the recipient already relies on it.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
The difference is less about which app has the longest feature list and more about the route that works for both sides. Skrill makes sense when its account, transfer options or online checkout presence match a specific need. I would skip it as my only payment method if the people I pay rarely use it, or if I mainly want a single place to manage banking and spending.
What to check before making it your default
For a first payment, I would begin with a small, ordinary transaction rather than moving a large amount immediately. That gives me a chance to learn where the recipient details appear, how the confirmation screen presents the payment and where to find the record afterward. It is a simple way to become comfortable with the workflow before depending on it for something time-sensitive.
I would also make a routine of checking the recipient and currency before confirming, especially when sending money internationally. Once a transfer is submitted, fixing a mistaken detail may be less straightforward than catching it on the review screen. For regular use, checking the history every so often helps me spot payments I no longer recognize and keeps the account from becoming an out-of-sight pocket of spending.
Who will get the most from it
I see Skrill as a stronger fit for someone who has a clear reason to use a digital payment account: paying online where it is supported, handling transfers with people who can receive them through the service, or keeping some payment activity separate from a main bank account. It is less compelling for someone who makes only occasional local purchases and already finds bank transfers or a mobile wallet effortless.
That distinction matters because adding an app is not the same as simplifying money management. If I have to move funds between accounts, remember another balance and check several places to understand my spending, the convenience may disappear. I would use Skrill for a defined job and keep my usual payment method for everything it handles more cleanly.
Getting Started with Ease
First things first, setting up Skrill is a breeze. All you need is to download the app, create an account, and you're ready to go. The user interface is super intuitive, which means you don't need to be a tech wizard to find your way around. I personally appreciated the step-by-step guidance during the setup process, ensuring that even the most tech-averse can get started without any hiccups.
Features That Stand Out
One of the standout features of Skrill is its versatility. Not only can you send and receive money, but you can also make online payments, all while keeping your financial information safe and secure. The app supports multiple currencies, which is a lifesaver if you're dealing with international transactions. I found the currency conversion feature particularly handy, as it provides real-time exchange rates, saving me the trouble of checking elsewhere.
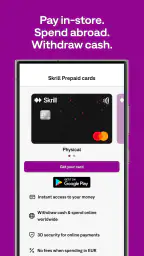
Another cool feature is the prepaid card option. You can apply for a Skrill Prepaid MasterCard, which links directly to your account. This card is fantastic for managing your spending, especially if you're like me and prefer to keep your online and offline finances separate. Plus, the app lets you track your spending in real-time, helping you stay on top of your budget.
Security You Can Trust
When it comes to handling money, security is paramount. Skrill uses state-of-the-art encryption technology to ensure that your transactions are safe from prying eyes. The app requires two-factor authentication, adding an extra layer of protection. I felt confident knowing that my financial data was in safe hands.
Additionally, the app offers a transaction history feature where you can review all your past transactions. This transparency is crucial for those who like to keep a close eye on their financial activities.
Wrapping Up
All in all, Skrill is more than just a payment app; it's a comprehensive financial tool that caters to a wide range of payment needs. Whether you're sending money across the globe or just paying for your morning coffee, this app has got you covered. The combination of user-friendly design, robust features, and top-notch security makes it a standout choice in the crowded world of payment apps.
If you're looking for a reliable, secure, and efficient way to handle your payments, I highly recommend giving Skrill a try. It's become a staple in my app arsenal, and I think it might just become a favorite of yours too!
A sensible way to test the switch
Moving from a familiar payment method can feel like a bigger commitment than installing an app. I would treat Skrill as a gradual addition: create the account, explore the available payment routes, and try a low-stakes transaction before making it part of a regular routine. That gives me a chance to see whether its flow suits me without depending on it for an urgent payment on day one.
I would keep an eye on the full journey, not just the moment I tap send. Check how you add or access funds, what the confirmation screen says, and how easily you can match a completed payment to a person or purchase later. If those steps feel clear and the app fits a payment I already make, the change has a purpose. If it means juggling balances without removing any real hassle, staying with a bank app or card is a perfectly sensible choice.
Costs, access and account habits
The app is free to install, but I would not treat that as proof that every way of using it is cost-free. Payment services can show different charges or conversion details depending on the transaction, so I would read the amount and terms presented for the exact action I am taking. This is particularly worthwhile when currencies differ: compare the amount the recipient is expected to get, rather than judging only by the exchange rate shown in isolation.
The prepaid card may also appeal if separating some spending from a main account is useful, but I would check its availability and applicable terms for my situation before planning around it. I would not assume that every account can use every option in the same way. A feature is only a practical advantage when it is available to you and its conditions suit the way you intend to pay.
For account safety, I would use a strong, unique password and keep the extra authentication step enabled. I would also review transaction records regularly rather than relying on memory, particularly if I use the account for both transfers and online purchases. These habits do not replace the app’s protections; they make it easier to notice an unfamiliar payment and respond promptly.
Who should look elsewhere
If you need a payment method that works everywhere, Skrill should not be your sole option. Acceptance varies by recipient and merchant, so a bank card or the payment method already supported at checkout can be the more dependable choice. Likewise, anyone who prefers all balances and transfers inside one banking app may find a separate payment account adds unnecessary administration.
It may also be a poor fit if you do not want to monitor another account or compare transaction terms when currencies are involved. I would not choose a money-transfer app simply because it has international features; I would choose it when the recipient can use it and the complete cost and process make sense for that specific payment. Keeping a backup method is sensible even after Skrill proves useful.
How the app fits the wider market
Digital wallets, bank transfers and dedicated payment services overlap, but each solves a slightly different problem. A wallet integrated with a phone can be convenient at supported checkouts, while a bank transfer may be easier when you and the recipient already share a familiar banking route. Skrill’s appeal is the combination of an account for transfers and online payments, with currency conversion tools and a transaction record in the same app.
That combination is useful, but it does not settle every comparison. For a one-off local payment, the fastest option may be the one both parties already have. For recurring online purchases, a card may involve fewer steps. For a cross-currency transfer, I would compare the final amount and process across the options available to me before deciding. In other words, Skrill is best judged as a useful route in a payment toolkit, not as a universal replacement for every other route.
Who is behind it and what to expect
Skrill is a finance app from Paysafe Holdings UK Limited. It is free to download, open to everyone by its age classification, and has been available since September 2014. Its 4.6 average from around 228,000 ratings, alongside more than 10 million installs, suggests that many people have found a reason to keep it in their payment mix. Those figures are useful context, but they do not tell me whether a particular recipient supports it or whether a transaction’s terms suit my needs.
The app’s current version is 3.174.0-2025112415, and it runs on Android 7.0 or later. I would still check the app’s current compatibility and account options on my own device before relying on it, especially if I use an older phone. Its broad reach makes it easy to consider, but the best test is whether its actual payment flow works for the people and services I deal with.
My recommendation
I would recommend Skrill to someone who regularly encounters it as a payment option, sends money to people who can receive it through the service, or values having a separate place for selected online transactions. The currency tools and transaction history can make those tasks easier to follow, while the prepaid card option may suit people who want to keep certain spending apart from their primary account.
I would not recommend making it your only way to pay before checking acceptance, transaction terms and the steps needed to use your account. Start with a small payment, learn where to review the record, and keep a familiar backup for merchants or recipients that do not support it. Used for the right job, Skrill can be a practical addition; used without a clear purpose, it can become one more balance to manage.
Frequently Asked Questions
What is Skrill and what are its main features?
Skrill is a digital wallet provider that offers fast, secure, and convenient payment solutions for both personal and business use. Users can send and receive money globally, pay for online purchases, and manage their finances with ease. Key features include instant transfers, low fees, support for multiple currencies, and a prepaid Mastercard option for easy withdrawals.
Is it safe to use Skrill for online transactions?
Yes, Skrill is considered safe for online transactions as it employs advanced security measures to protect users' data and funds. It uses encryption and two-factor authentication to ensure secure transactions. Additionally, Skrill is regulated by the Financial Conduct Authority (FCA) in the UK, providing an extra layer of security and consumer protection.
How can I create a Skrill account and is there any cost involved?
Creating a Skrill account is straightforward and free of charge. Users need to provide basic personal information and verify their identity through a simple process. Once the account is set up, users can fund it using various methods like bank transfers, credit/debit cards, or other e-wallets. While account creation is free, some services may incur fees, such as currency conversion or withdrawals.
What currencies does Skrill support and can I hold multiple currencies in my account?
Skrill supports a wide range of currencies, making it convenient for users who transact globally. Users can hold multiple currencies within their account, allowing them to manage their international transactions more effectively. This feature also helps in minimizing currency conversion fees when sending or receiving money in different currencies.
Are there any transaction limits with Skrill, and how can I increase them?
Skrill imposes transaction limits to ensure secure handling of funds. These limits vary based on account verification level and usage history. To increase your transaction limits, you can complete additional verification steps, such as providing more detailed identity information. Enhanced verification not only increases limits but also adds more security to your account.


